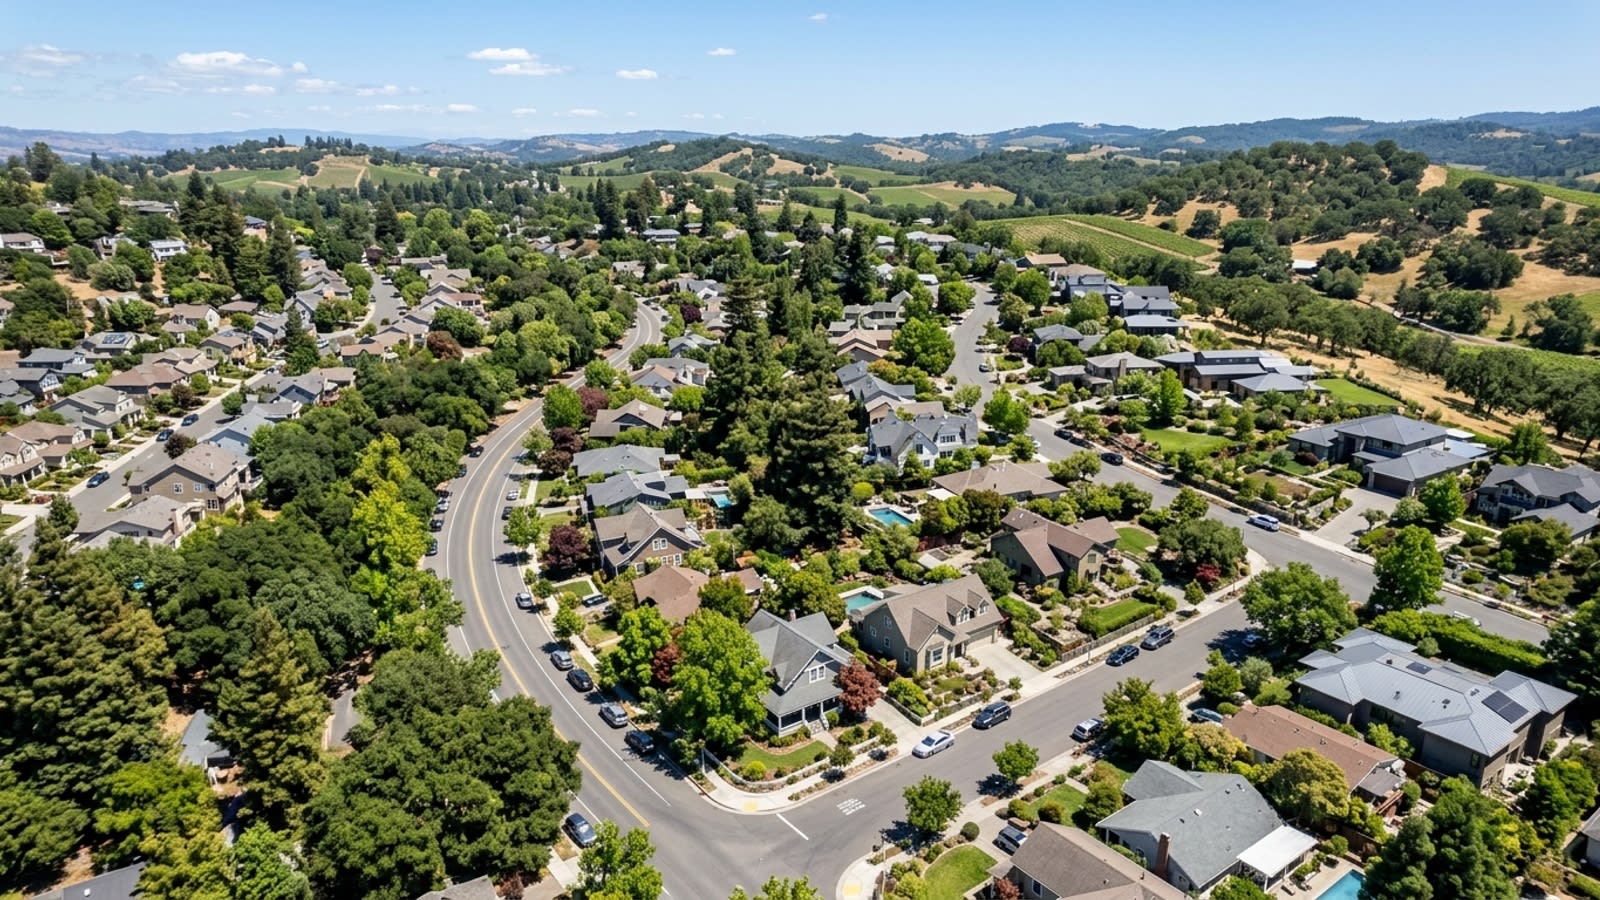
The median home sale price in Healdsburg, CA sits around $1,329,000. Available homes are spending roughly 40 days on the market and selling at about 97.7% of list price - that's not a forgiving environment for first-time home buyers in Healdsburg who are short on cash at the closing table.
Getting into Sonoma County real estate often comes down to one thing: finding the right financing before you find the right house. First-time homebuyer programs offer grants, deferred loans, and down payment assistance designed to cover the difference between what you've saved and what you actually need to close.
Overview of First-Time Buyer Programs in Healdsburg
Healdsburg doesn't run its own municipal down payment assistance fund, so local buyers work with a network of state and county options instead. That means leaning on the California Housing Finance Agency (CalHFA), the Golden State Finance Authority (GSFA), and various Sonoma County partnerships.
How the money is structured depends on who's providing it. You might access a non-repayable grant, a silent second mortgage with no monthly payments, or a fully amortizing secondary loan at a low interest rate - each one works differently and comes with its own strings.
Who Qualifies as a First-Time Buyer in California
State and county programs use a standard three-year lookback to define first-time buyers. If you haven't held an ownership interest in your primary residence at any point during the past three years, you meet the basic definition.
That rule applies to everyone on the loan application. If you're buying with a partner who owned property last year, their recent ownership history disqualifies the joint application from first-time buyer status - regardless of your own history.
Types of Assistance Available
The most common form of help is a deferred-payment junior loan, often called a silent second mortgage. It sits behind your primary mortgage, accrues interest, and requires no monthly payments until you sell the home, refinance, or pay off the first mortgage.
Beyond that, you'll find direct grants that never need to be repaid, and standard second mortgages that do require immediate monthly payments. Which type you end up with depends entirely on the agency and lender you choose.
Statewide Grants and Deferred Loans
CalHFA and GSFA run the two largest assistance funds available to Healdsburg buyers. Neither agency lends directly to consumers - they route funds through approved local mortgage lenders who do the actual underwriting.
The assistance amounts scale with your purchase price or primary mortgage size. Given that Healdsburg home prices regularly clear $1 million, maximizing these percentage-based programs is a common move for buyers trying to cover a 3% or 5% minimum down payment.
How Much Assistance is Available
CalHFA's MyHome program offers a deferred second loan of up to 3.5% of the purchase price or appraised value when paired with an FHA first mortgage. Pair it with a Conventional, VA, or USDA first mortgage instead, and the cap drops to 3% - which translates to about $15,000 on a $500,000 purchase.
The GSFA Platinum program goes further, offering up to 5.5% of your first mortgage loan amount. You can take it as a non-repayable grant tied to a slightly higher rate on your primary mortgage, or as a repayable 15-year amortizing second loan.
How to Apply for State Aid
You apply for CalHFA and GSFA funds through a private loan officer who's approved to originate these specific products. Not every bank or broker has those credentials.
Your loan officer will pull your credit, verify your income, and reserve the state funds on your behalf during pre-approval. Confirm your lender's approval status with these agencies before you let anyone run your credit.
Down Payment Assistance in Sonoma County
Buyers inside Healdsburg city limits won't find a dedicated municipal program - the city doesn't fund its own down payment assistance. What you'll find instead are regional funds managed at the county level.
Sonoma County has several assistance pathways worth knowing, including the Burbank Housing Down Payment Assistance Program and the GSFA Assist-To-Own initiative. These carry their own income caps and funding cycles, so they don't always behave like their state-level counterparts.
Local County and Regional Programs
County employees have access to something specific: the Sonoma County/SEIU Housing Assistance Committee (HAC). That program offers a fully amortized 15-year loan equal to 6% of the sales price, capped at a maximum of $10,000, at a 3% interest rate.
Some buyers also look at the City of Santa Rosa Down Payment Assistance Loan (DPAL) Program when their search expands south of Healdsburg. DPAL doesn't apply to Healdsburg addresses, but it's a significant regional option for anyone keeping their search broad across Sonoma County.
Forgivable Loans vs. Second Mortgages
Pay close attention to the repayment terms when you're evaluating Sonoma County programs. A forgivable loan functions like a grant if you stay in the home long enough - the debt gradually disappears over a set number of years.
A standard second mortgage, like the SEIU HAC loan, requires monthly principal and interest payments from day one after closing. You'll need to factor those payments into your total debt-to-income ratio before you start making offers.
Income Limits and Eligibility Rules
Every assistance program sets strict financial boundaries to keep funds going to moderate- and low-income households. Agencies review your household income, your credit profile, and the final purchase price of the property.
Qualifying income is calculated on your gross earnings - bonuses, overtime, and part-time wages all count. If your total household income exceeds the published caps, the lender will deny the assistance application.
Income and Purchase Price Caps
CalHFA sets a statewide income floor of $192,000 for 2026 for its subordinate loan programs. The exact 2026 cap for Sonoma County fluctuates based on HUD data, so check CalHFA's official limits page for the current number rather than relying on anything secondhand.
The HUD income limits for Sonoma County, which affect other regional housing programs, updated on June 1, 2026. These figures adjust annually - verify the current caps with your lender at the very start of your search, not after you're already in contract.
Minimum Credit Score Rules
CalHFA requires a minimum credit score of 640 for its FHA loan options and 680 for conventional loans. If you're buying a manufactured home or using manual underwriting on an FHA file, that minimum bumps up to 660.
The GSFA Platinum program generally requires a minimum FICO score of 640, with maximum debt-to-income ratios capped around 45% to 50%. Get your score to 700 or higher and CalHFA will allow your debt-to-income ratio to stretch up to 50%, which opens up more borrowing room.
Federal Loan Options for Local Buyers
State and county assistance funds don't stand alone - they have to attach to a primary mortgage. The loan type you choose dictates your down payment requirement and shapes which assistance programs you can actually use.
Most buyers pairing a primary mortgage with down payment aid go with a government-backed loan. Lower barrier-to-entry requirements make them natural vehicles for first-time buyers who need to preserve cash.
FHA, VA, and USDA Loans
FHA loans require a 3.5% down payment and accept lower credit scores, which makes them the most common pairing for CalHFA and GSFA funds. VA loans offer zero-down financing for eligible veterans and active-duty service members, and they can stack with state aid to cover closing costs.
USDA loans provide zero-down financing for properties in eligible rural areas. Central Healdsburg doesn't qualify, but some properties on the outskirts of Sonoma County do fall into USDA-eligible zones.
Combining Federal Loans with Local Aid
Pair an FHA loan with CalHFA's MyHome program and that 3.5% deferred loan can cover the FHA down payment requirement entirely. Done right, this structure lets you close on a home with very little of your own cash going out the door.
You'll need to complete a HUD-approved homebuyer education course to use these combinations. Lenders require that completion certificate before they'll issue a clear-to-close on any state-backed assistance file - don't wait until the last minute to take it.
Frequently Asked Questions
What are the income limits to qualify for first-time homebuyer assistance in Healdsburg, CA?
It depends on the program. CalHFA sets a statewide floor of $192,000 for 2026, but the specific cap for Sonoma County varies based on HUD data updated on June 1, 2026. Check the official CalHFA and GSFA county-by-county tables for the exact current figures.
How do I apply for the City of Healdsburg's down payment assistance program?
There isn't one. Healdsburg doesn't offer a city-specific down payment program, so buyers purchasing there need to use Sonoma County-wide options like Burbank Housing or state programs like CalHFA and GSFA - all of which you apply for through an approved private mortgage lender.
Can I combine Sonoma County housing grants with Healdsburg city-specific buyer programs?
No, because no Healdsburg city-specific buyer programs exist to combine. You can, however, layer Sonoma County resources - like the SEIU Housing Assistance Committee loan for county employees - with state-level CalHFA or GSFA funds.
Are there designated Below Market Rate (BMR) homes available for purchase in Healdsburg?
The available county data doesn't list a specific inventory of Below Market Rate homes managed by the City of Healdsburg. Buyers looking for affordable housing programs generally rely on Sonoma County's broader assistance options and state-backed financing.
Do I have to pay back the local down payment assistance if I sell my Healdsburg home or refinance?
In most cases, yes. Programs like CalHFA's MyHome issue deferred loans that come due when you sell, refinance, or pay off the primary mortgage. The exception is specific non-repayable grants - like the one offered through GSFA Platinum - which don't require repayment.
How long does it typically take to get approved for local buyer assistance in Healdsburg?
It varies by lender and by the specific agency providing the funds. Because you apply through an approved private lender, the assistance approval generally follows the same timeline as your primary mortgage underwriting process.