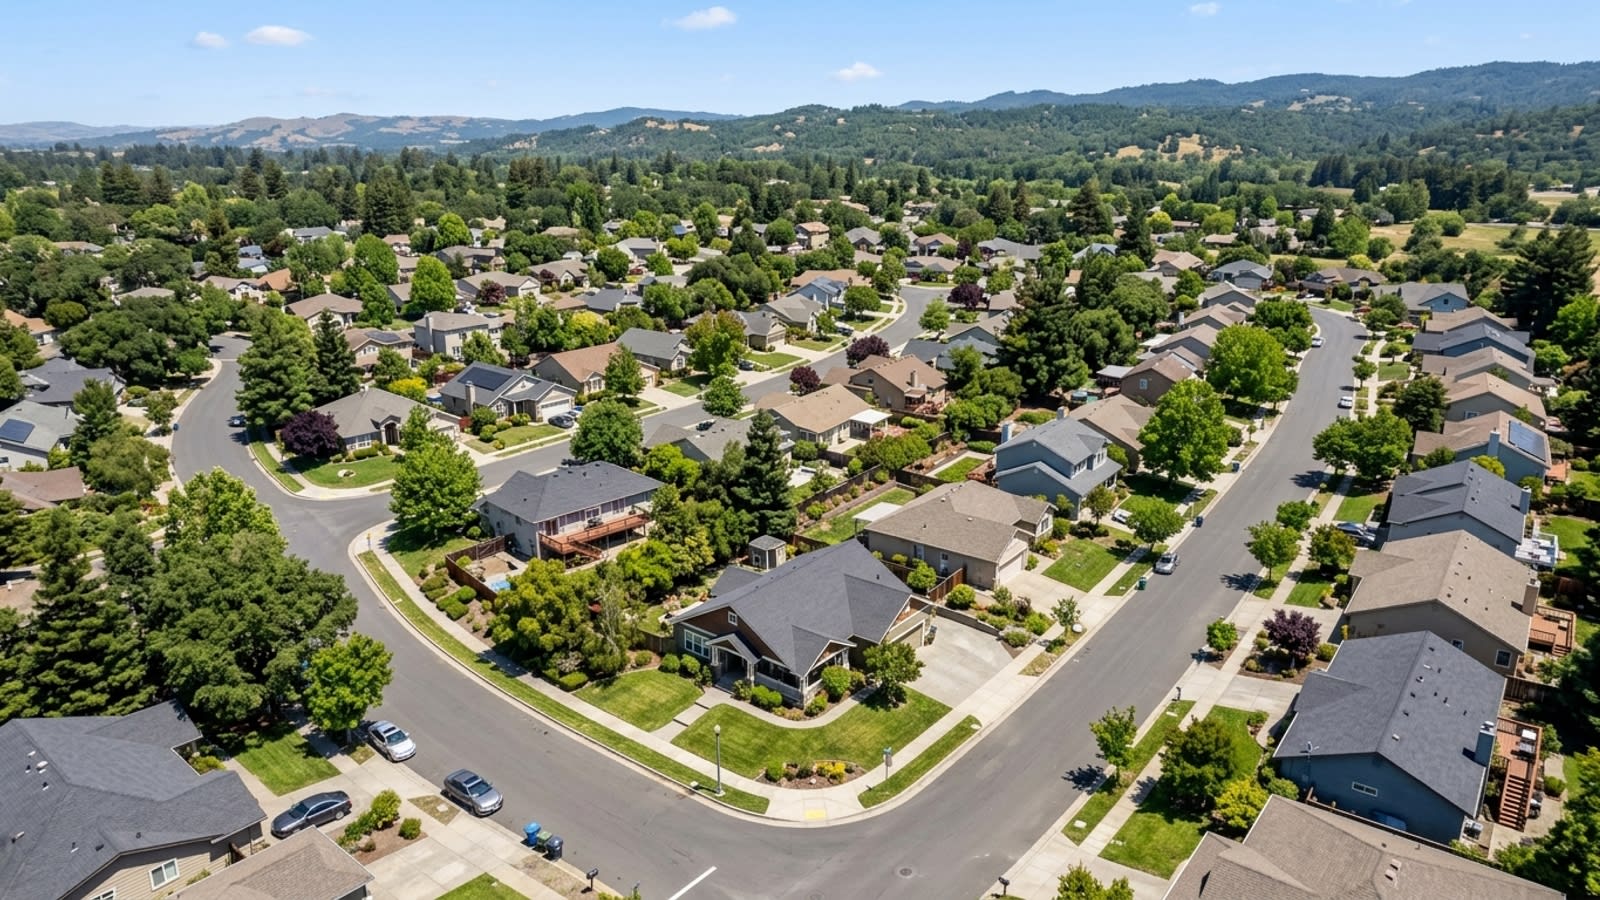
The median home sale price in Windsor, CA, sits around $824,500, and homes are moving - roughly 32 days on market with only about 59 homes available. That's not a lot of runway to get your financing sorted as a first-time home buyer in Windsor, CA.
The current lending climate and the loan limits that actually apply to this area matter more than most buyers realize. The programs available to you can shift significantly depending on household income, down payment size, and which loan type you're working with.
Current Interest Rates for Windsor Buyers
As of August 2026, the average 30-year fixed mortgage rate in California runs approximately 6.75% to 7.00%. Some trackers caught rates dipping a bit lower, with 30-year fixed mortgages averaging 6.54% APR in late August. Those are averages - your actual rate depends on your credit profile and which lender you're sitting across from.
One thing buyers often overlook: the difference between the interest rate and the Annual Percentage Rate (APR). The APR folds in broker fees and other closing costs, so it reflects the actual cost of the loan. Always compare both numbers when you're evaluating offers.
Comparing Fixed-Rate Options
Most buyers go with the 30-year fixed because it keeps monthly payments manageable. The 15-year fixed is cheaper in rate terms - currently averaging around 6.12% to 6.16% in California - but the monthly payment is meaningfully higher.
You pay less total interest over the life of a 15-year loan. Whether that trade-off makes sense depends entirely on what your budget can actually absorb each month.
How Adjustable-Rate Mortgages Work
An adjustable-rate mortgage gives you a fixed rate for an initial period - typically five or seven years - then adjusts annually based on market conditions.
ARMs sometimes come in lower than a 30-year fixed at the start. If you know you're selling or refinancing before that fixed window closes, it can be a reasonable way to save on interest in the short term. If you're not confident about that timeline, the unpredictability after the adjustment kicks in is real.
Sonoma County Loan Limits for 2026
The Federal Housing Finance Agency sets limits on what government-sponsored entities will back. For 2026, the baseline conforming loan limit for a one-unit property in California is $832,750 - up 3.26% from the previous year.
Sonoma County qualifies for a higher threshold because of local housing costs. The 2026 high-balance conforming loan limit for Sonoma County is $897,000. Go above that and you're in jumbo territory, which typically means a larger down payment and tighter underwriting.
Conventional Conforming Limits
For borrowers with solid credit, conventional loans under the $897,000 Sonoma County high-balance limit offer real flexibility. Buy a median-priced Windsor home at $824,500 with 10% down and your loan comes to roughly $742,000 - well inside conforming limits. Put 20% down and you're looking at about $164,900 upfront, with a loan of approximately $659,600. Either way, you stay within the range where standard conventional products and rates apply.
FHA and VA Loan Caps
The high-balance FHA loan limit for a single-unit property in Sonoma County matches the conforming limit at $897,000 for 2026. That means buyers using FHA financing can purchase a median-priced Windsor home with as little as 3.5% down.
VA loans in California have no county loan limit for veterans with full entitlement - eligible buyers can borrow above the conforming limit without a down payment. For partial-entitlement VA borrowers, the Department of Veterans Affairs references the $897,000 Sonoma County conforming limit.
Down Payment Assistance and Buyer Programs
Several programs exist specifically to help Sonoma County buyers cover upfront costs, and they're worth knowing about before you assume you need to come in with a large chunk of cash.
Eligibility generally comes down to household income, first-time buyer status, and the property's purchase price. The California Housing Finance Agency (CalHFA) offers 30-year, fixed-rate FHA, conventional, VA, or USDA mortgages that can be paired with down payment assistance - though you'll need to complete a homebuyer education course and meet specific income thresholds to qualify.
State-Level CalHFA Programs
CalHFA's MyHome program covers up to 3.5% of the purchase price for down payment or closing costs through a deferred-payment second loan. The Zero Interest Program (ZIP) adds up to 3% of the total loan amount as a no-interest second loan for closing costs. Neither is forgiven - both become due when you sell, refinance, or transfer the property.
CalHFA's Dream For All program, which provided up to 20% in assistance, closed in July 2026. MyHome and ZIP remain open year-round.
Local Sonoma County Assistance
The Sonoma County SEIU First Time Home Buyer Program offers eligible SEIU Local 1021 county employees up to $100,000 in fully amortized secondary mortgage financing at below-market rates. That's a meaningful number if you qualify.
The Golden State Finance Authority (GSFA) Platinum Program provides up to 5.5% of the loan amount in assistance and is open to both first-time and repeat buyers. Sonoma County buyers can also look at a Mortgage Credit Certificate (MCC) - a federally backed tax credit issued locally that directly reduces your federal income tax liability.
Securing Financing for a Windsor Home
With Windsor homes spending a median of 32 days on market, you don't have time to figure out financing after you find the house you want. Sellers expect a pre-approval letter, and the local market backs that up - roughly 40% of homes here sell above list price. A strong pre-approval from a reputable lender tells a seller you can actually compete.
Preparing Your Financial Profile
Lenders look at your credit score, debt-to-income ratio, and employment history when pricing your rate. Paying down existing debt and keeping your payment history clean before you apply is the most direct way to improve your position.
Don't open new credit lines or make large purchases while you're in the middle of a mortgage application. Any sudden shift in your credit profile can slow down underwriting or change what you're approved for.
Shopping for Lenders
Local lenders, credit unions, and national banks each have different products and fee structures. Pull Loan Estimates from multiple sources and compare interest rates, origination fees, and closing costs side by side - that's the only way to know what you're actually being offered.
Some local lenders know regional programs like the GSFA Platinum Program or specific Sonoma County options better than others. That familiarity can make a difference in how smoothly your application moves.
Frequently Asked Questions
Are mortgage rates in Windsor, CA typically higher or lower than the rest of Sonoma County?
No, local rates track closely with broader Sonoma County trends rather than carrying a city-specific premium. Since lenders price loans based on individual risk factors, improving your credit score or increasing your down payment will impact your final rate much more than the property's zip code.
What credit score are local Windsor lenders currently requiring to qualify for their best interest rates?
It depends on the specific lender and the loan type you choose. Conventional loans generally require higher credit scores for optimal pricing, while FHA loans offer more flexibility for buyers with lower scores.
Are there any first-time homebuyer programs in Windsor that offer discounted mortgage rates?
While city-specific rate discounts are rare, buyers can lower their effective borrowing costs through regional programs. First-time buyers should verify if their household income qualifies for a Mortgage Credit Certificate, which provides a direct federal tax credit that can make monthly payments more affordable.
At what point during the Windsor home buying process should I lock in my mortgage rate?
Most buyers secure their rate immediately after going under contract on a property. Because market conditions fluctuate daily, having your pre-approval completed before you shop ensures you can lock in terms the moment a seller accepts your offer.
What happens if interest rates drop while I am in escrow on a house in Windsor?
It depends on your lender's policies and whether you secured a float-down option when you initially locked your rate. A float-down provision allows you to lower your locked interest rate if market rates fall before your closing date.
Do mortgage rates differ if I am buying a new construction home in Windsor versus an older property?
No, standard mortgage rates apply regardless of the home's age. Some builders do offer rate buydowns or specialized financing incentives through their preferred lenders to attract buyers to new developments.